Long Island Mortgage Rates Top 7% This Fall: How a 2-1 Buydown, a 5/1 ARM or a Seller Credit Can Cut Your Nassau or Suffolk Payment by Up to $937 a Month For the first time since January 2025, the

Dated: October 11 2024
Views: 67
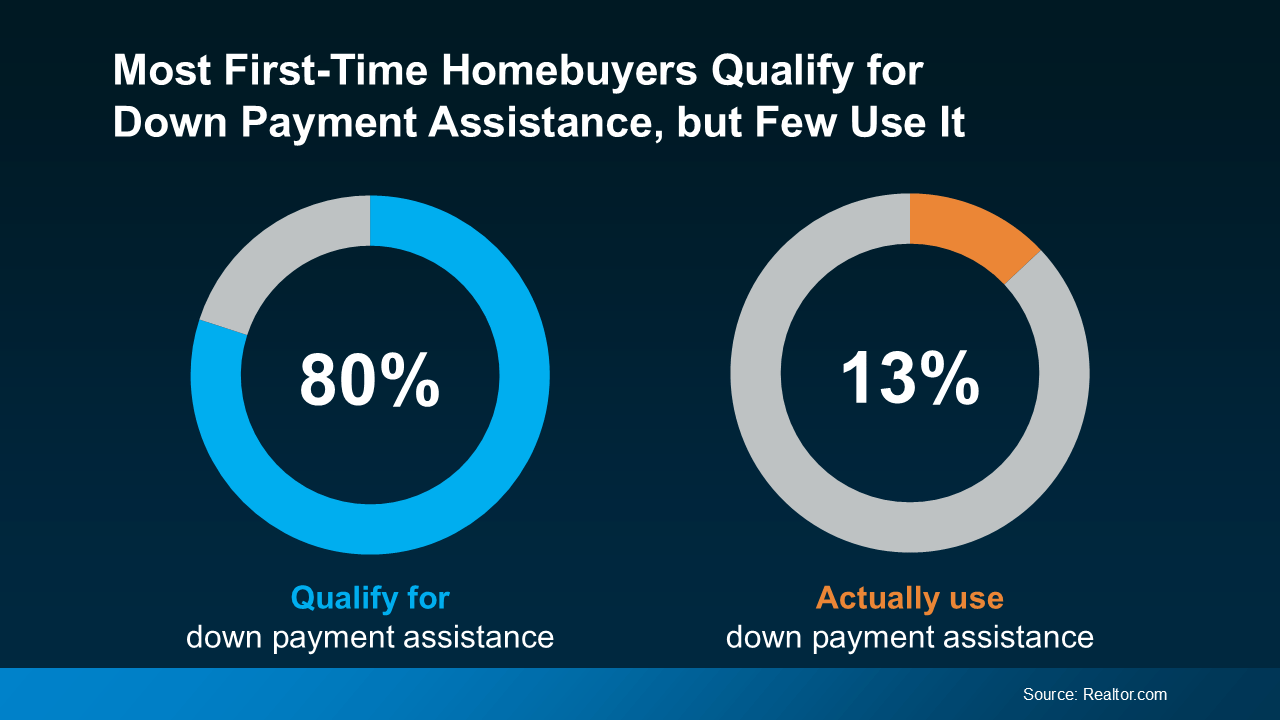
Believe it or not, almost 80% of first-time homebuyers qualify for down payment assistance, but only 13% actually use it. And if you’re hoping to buy a home, this is a mission-critical gap to close – fast (see graph below):
 Here’s what you need to know to make the most of your down payment in today’s housing market.
For first-time buyers, the name of the game with down payments is making sure you’re taking advantage of all the resources out there designed to help you. And a bunch of them can get you to your goal faster than you may have thought possible.
For example, there are loan options that require as little as 3% down, or even 0% for certain qualified borrowers, like Veterans. And let’s not forget down payment assistance, like grants and other opportunities, that help you cover the upfront cost of your down payment.
If you’re interested in exploring those options and what you may be able to use to your advantage, connect with a trusted lender. Because if you don't at least see what’s available, you could be leaving money on the table and missing your chance at buying a home. These resources can boost your down payment. And a higher down payment could help lower your eventual monthly mortgage payment, and even avoid or reduce your fees like private mortgage insurance.
There’s one more thing to address. News coverage has been talking about how the typical down payment is rising. A report from Redfin states:
“The typical down payment for U.S. homebuyers hit a record high of $67,500 in June, up 14.8% from $58,788 a year earlier . . . This was the 12th consecutive month the median down payment rose year over year.”
But don’t let those high dollars scare you. Just because the average down payment is rising doesn’t mean down payment requirements are going up. That’s a key piece of the puzzle to understand. It’s really just because people are choosing to put more down to try to offset higher mortgage rates, and current homeowners who are putting their equity to work are using that to increase their down payment on their next home. As HousingWire explains:
“. . . buyers are putting down a higher percentage of the purchase price to lower their monthly mortgage payment. And buyers also had more equity from their home sales, which gives them more cushion.”
Let’s break those two reasons down a bit:
1. A bigger down payment helps lower your monthly mortgage payment.Affordability has been a challenge for many buyers recently, which is why those who have the ability to make a bigger down payment are going to do so in an effort to lower their future housing costs.
2. Buyers who already own a home have a record amount of equity to leverage.Someone who bought a home a few years ago has gained a significant amount of value in their house, thanks to home price appreciation. These people can put down much more than the average first-time buyer who hasn’t owned a home yet.
What’s the best thing to do? Talk with a trusted lender about your options. They’ll help you figure out where you stand today and how to access the resources you may qualify for. Because help is out there, you just need to work with a pro to take advantage of it.
Best Realtor In Syosset, Best Syosset Realtor, Giulio Ferrante, Signature Premier Properties
#BuySellHomesLI
#SignaturePremierProperties
#ListYourHome
#SellYourHome
#RealEstate
#LongIslandHomes
#LIRealEstate
#LongIslandRealtor
#NYRealEstate
#HomeBuyersLI
Giulio Ferrante, representing Signature Premier Properties, stands as one of the industry's most trusted and top-selling real estate agents. With a focus on Long Island, particularly in Syosset, amids....
Long Island Mortgage Rates Top 7% This Fall: How a 2-1 Buydown, a 5/1 ARM or a Seller Credit Can Cut Your Nassau or Suffolk Payment by Up to $937 a Month For the first time since January 2025, the
Long Island Home Prices Top $900,000 as Mortgage Rates Break 7%: What the Fed's September Hike Means for Nassau and Suffolk Buyers and Sellers This Fall Two numbers landed on Long Island within a
Median sale prices tell you what a house cost. Price per square foot tells you what you actually bought. Right now on Long Island that number ranges from about $365 a square foot in parts of South
Long Island Real Estate Attorney Fees and the Contract Timeline in 2026: What a $2,250 Flat Fee, an $84,000 Escrow Deposit and 2-7 Days of Attorney Review Really Mean for Your Nassau or Suffolk
 OneKey® MLS required Copyright, Source of Data and Disclaimer for IDX display
Information Copyright 2026, OneKey® MLS. All Rights Reserved.
The source of the displayed data is either the property owner or public record provided by non-governmental third parties. It is believed to be reliable but not guaranteed. This information is provided exclusively for consumers' personal, non-commercial use.
The data relating to real estate for sale on this website comes in part from the
IDX Program of OneKey® MLS.
33. Required DMCA Notice
The Digital Millennium Copyright Act of 1998, 17 U.S.C. §512, the DMCA, provides recourse for copyright owners who believe that material appearing on the Internet infringes their rights under U.S. copyright law. If you believe in good faith that any content or material made available in connection with our website or services infringes your copyright, you (or your agent) may send us a notice requesting that the content or material be removed, or access to it blocked. Notices must be sent in writing by email to DMCAnotice@MLSGrid.com. The DMCA requires that your notice of alleged copyright infringement include the following information: (1) description of the copyrighted work that is the subject of claimed infringement; (2) description of the alleged infringing content and information sufficient to permit us to locate the content; (3) contact information for you, including your address, telephone number and email address; (4) a statement by you that you have a good faith belief that the content in the manner complained of is not authorized by the copyright owner, or its agent, or by the operation of any law; (5) a statement by you, signed under penalty of perjury, that the information in the notification is accurate and that you have the authority to enforce the copyrights that are claimed to be infringed; and (6) a physical or electronic signature of the copyright owner or a person authorized to act on the copyright owner\'s behalf. Failure to include all of the above information may result in the delay of the processing of your complaint.
Show More...