
Long Island Mortgage Rates Top 7% This Fall: How a 2-1 Buydown, a 5/1 ARM or a Seller Credit Can Cut Your Nassau or Suffolk Payment by Up to $937 a Month For the first time since January 2025, the

Dated: October 11 2024
Views: 65
Why a Foreclosure Wave Isn’t on the Horizon
Tuesday July 23rd, 2024 Foreclosures, Forecasts
Even though data shows inflation is cooling, a lot of people are still feeling the pinch on their wallets. And those high costs on everything from gas to groceries are fueling unnecessary concerns that more people are going to have trouble making their mortgage payments. But, does that mean there’s a big wave of foreclosures coming?
Here's a look at why the data and the experts say that’s not going to happen.
There Aren’t Many Homeowners Who Are Seriously Behind on Their Mortgages
One of the main reasons there were so many foreclosures during the last housing crash was because relaxed lending standards made it easy for people to take out mortgages, even when they couldn’t show they’d be able to pay them back. At that time, lenders weren’t being as strict when looking at applicant credit scores, income levels, employment status, and debt-to-income ratio.
But since then, lending standards have gotten a whole lot tighter. Lenders became much more diligent when assessing applicants for home loans. And that means we’re seeing more qualified buyers who have less of a risk of defaulting on their loans.
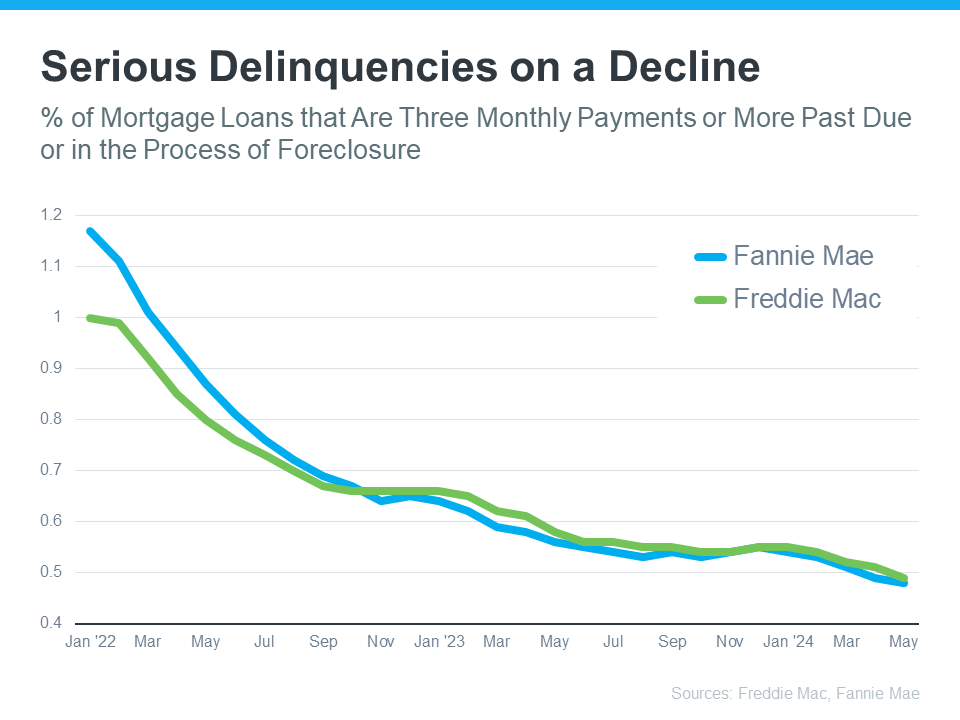
That’s why data from Freddie Mac and Fannie Mae shows the number of homeowners who are seriously behind on their mortgage payments (known in the industry as delinquencies) has been declining for quite some time. Take a look at the graph below:
What this means is that, not only are borrowers more qualified, but they’re also finding ways to navigate through their challenges, exploring their repayment options, or maybe even using the record amount of equity they have to sell and avoid foreclosure entirely.
The Answer Is: There’s No Sign of a Wave Coming
Before there can be a significant rise in foreclosures, the number of people who can’t make their mortgage payments would need to rise significantly. But, since so many buyers are making their payments today and homeowners have so much equity built up, a wave of foreclosures isn’t likely.
Take it from Bill McBride of Calculated Risk – an expert on the housing market who, after closely following the data and market leading up to the crash, was able to see the foreclosure crisis coming in 2008. McBride says:
“We will NOT see a surge in foreclosures that would significantly impact house prices (as happened following the housing bubble) for two key reasons: 1) mortgage lending has been solid, and 2) most homeowners have substantial equity in their homes.”
Bottom Line
If you’re worried about a potential foreclosure crisis, know there’s nothing in the data to suggest that’ll happen. Buyers are more qualified now, and that’s one reason why they’re not falling seriously behind on their mortgage payments.
Best Realtor In Syosset, Best Syosset Realtor, Giulio Ferrante, Signature Premier Properties
#BuySellHomesLI
#SignaturePremierProperties
#ListYourHome
#SellYourHome
#RealEstate
#LongIslandHomes
#LIRealEstate
#LongIslandRealtor
#NYRealEstate
#HomeBuyersLI
Giulio Ferrante, representing Signature Premier Properties, stands as one of the industry's most trusted and top-selling real estate agents. With a focus on Long Island, particularly in Syosset, amids....
Long Island Mortgage Rates Top 7% This Fall: How a 2-1 Buydown, a 5/1 ARM or a Seller Credit Can Cut Your Nassau or Suffolk Payment by Up to $937 a Month For the first time since January 2025, the
Long Island Home Prices Top $900,000 as Mortgage Rates Break 7%: What the Fed's September Hike Means for Nassau and Suffolk Buyers and Sellers This Fall Two numbers landed on Long Island within a
Median sale prices tell you what a house cost. Price per square foot tells you what you actually bought. Right now on Long Island that number ranges from about $365 a square foot in parts of South
Long Island Real Estate Attorney Fees and the Contract Timeline in 2026: What a $2,250 Flat Fee, an $84,000 Escrow Deposit and 2-7 Days of Attorney Review Really Mean for Your Nassau or Suffolk
 OneKey® MLS required Copyright, Source of Data and Disclaimer for IDX display
Information Copyright 2026, OneKey® MLS. All Rights Reserved.
The source of the displayed data is either the property owner or public record provided by non-governmental third parties. It is believed to be reliable but not guaranteed. This information is provided exclusively for consumers' personal, non-commercial use.
The data relating to real estate for sale on this website comes in part from the
IDX Program of OneKey® MLS.
33. Required DMCA Notice
The Digital Millennium Copyright Act of 1998, 17 U.S.C. §512, the DMCA, provides recourse for copyright owners who believe that material appearing on the Internet infringes their rights under U.S. copyright law. If you believe in good faith that any content or material made available in connection with our website or services infringes your copyright, you (or your agent) may send us a notice requesting that the content or material be removed, or access to it blocked. Notices must be sent in writing by email to DMCAnotice@MLSGrid.com. The DMCA requires that your notice of alleged copyright infringement include the following information: (1) description of the copyrighted work that is the subject of claimed infringement; (2) description of the alleged infringing content and information sufficient to permit us to locate the content; (3) contact information for you, including your address, telephone number and email address; (4) a statement by you that you have a good faith belief that the content in the manner complained of is not authorized by the copyright owner, or its agent, or by the operation of any law; (5) a statement by you, signed under penalty of perjury, that the information in the notification is accurate and that you have the authority to enforce the copyrights that are claimed to be infringed; and (6) a physical or electronic signature of the copyright owner or a person authorized to act on the copyright owner\'s behalf. Failure to include all of the above information may result in the delay of the processing of your complaint.
Show More...